The Market Shift: LFP Is Now the Default Solar Chemistry
Lithium iron phosphate now accounts for well over 90% of new stationary storage capacity added globally, a reversal from 2018 when NMC chemistries held a meaningful share of grid-scale deployments. According to BloombergNEF's Energy Storage Outlook, global energy storage installations are on track to reach roughly 411 GW / 1,194 GWh by 2030, and the overwhelming majority of that pipeline is LFP-based. The IEA's tracking of battery deployment similarly shows stationary storage as the fastest-growing battery segment after passenger EVs, with solar co-location representing the dominant project configuration in the US, China, and Australia.
Price is the primary driver. BloombergNEF's 2024 Lithium-Ion Battery Price Survey recorded a volume-weighted average pack price of $115/kWh, a 20% year-on-year decline, while Chinese LFP cell spot prices fell below $60/kWh in 2025—levels that make four-hour storage economically competitive with gas peakers in most sunny markets. Turnkey four-hour BESS benchmarks of roughly $269/kWh globally, and substantially lower in China, reflect the combined effect of cell oversupply, larger form factors, and manufacturing scale.
Policy has reinforced the trend. The US Section 45X manufacturing credit provides $35/kWh for cells and $10/kWh for modules produced domestically, while the EU Battery Regulation (2023/1542) introduces battery passports from February 2027 and recycled-content thresholds. For developers specifying solar-plus-storage, the practical consequence is a market where LFP supply is deep, warranties are standardized, and differentiation has shifted to system integration rather than cell chemistry itself.
Cell-Level Advances: From 314 Ah to 600 Ah and Beyond
The prismatic cell capacity race has accelerated sharply. The 280 Ah cell that defined 2021-era BESS designs gave way to 314 Ah as the 2024 workhorse, and by 2025 tier-one manufacturers were shipping or sampling 587 Ah, 625 Ah, and 688 Ah formats. Larger cells reduce the number of components per rack, cut busbar and sensing overhead, and improve volumetric efficiency—CATL's 587 Ah cell, for example, supports a 20-foot container rating of 6.25 MWh with a claimed five-year zero-degradation warranty.
Parallel to the format race, lithium manganese iron phosphate (LMFP) has entered commercial sampling. By incorporating manganese into the olivine structure, LMFP raises cell-level energy density roughly 15–20% above standard LFP—approaching 200–230 Wh/kg at cell level—while retaining the thermal stability profile that made LFP attractive. The trade-off is a flatter voltage curve that complicates state-of-charge estimation and, in early generations, marginally faster capacity fade. Suppliers are pairing LMFP with blended LFP cathodes to balance energy density against cycle life.
Manufacturing innovation matters as much as chemistry. Thicker electrodes, dry-electrode coating, tabless architectures, and cell-to-pack integration all reduce inactive mass. BYD's blade-format LFP cells—long, thin prisms used structurally in vehicles and increasingly in stationary racks—illustrate how geometry, not just chemistry, drives cost and density. For solar integrators, the takeaway is that cell choice should be evaluated on full-system metrics: $/kWh installed, cycles to 70% state of health, and thermal management burden.
System Architecture: 6+ MWh Containers, Smart BMS, and Grid-Forming
At the system level, 2025's defining product category is the 20-foot, liquid-cooled DC block rated above 6 MWh. CATL's TENER platform (6.25 MWh) and BYD's MC Cube-T (6.9 MWh) are representative, achieving footprint energy densities well above 150 kWh/m² compared with roughly 100 kWh/m² for 2022-era 3.7 MWh containers. Higher DC voltage—up to 1,500 V—reduces current and cable losses, and DC round-trip efficiency for modern LFP blocks typically lands between 92% and 96%, translating to 85–89% AC-to-AC.
Battery management has become a software discipline. Contemporary BMS platforms use electrochemical impedance spectroscopy and differential voltage analysis to estimate state of health cell-by-cell, enabling active balancing, early detection of lithium plating, and cell-level augmentation decisions. Cloud-connected analytics allow operators to compare rack performance against warranty curves, a capability that matters when a 20-year performance guarantee is at stake. According to NREL's storage reliability research, cell-level monitoring is one of the strongest predictors of avoided unplanned downtime.
Integration with inverters is the next frontier. Grid-forming inverter controls, compliant with IEEE 1547-2018 in the US and equivalent European codes, allow LFP blocks to provide synthetic inertia, fast frequency response, and voltage support—services that were previously the domain of synchronous machines. Pairing these capabilities with co-located PV requires careful DC/AC ratio planning and inverter oversizing; our [inverter technology overview](/tech/inverters) covers the sizing principles in more detail.
Field Data: Cycling, Temperature, and Real Degradation
Nameplate cycle life for LFP has climbed from 4,000–6,000 cycles in 2019 to 8,000–12,000 cycles at 25°C and 0.5C in 2025, with premium cells claiming 15,000. These figures, however, are laboratory conditions. NREL and PNNL field studies consistently show that real-world capacity fade is dominated by temperature exposure and average state of charge rather than cycle count alone—cells held at high SOC in hot climates can lose 2–3% per year, whereas well-managed systems in temperate zones fade at 1–1.5% annually.
Thermal management is therefore the single most consequential design decision. Liquid-cooled systems typically hold cell-to-cell delta within 2–3°C, compared with 5–8°C for air-cooled equivalents, and that uniformity directly extends pack life. Charging below 0°C remains restricted for LFP due to lithium plating risk, so cold-climate projects need integrated heaters or charge-current derating; discharge capability extends to roughly −20°C with modest capacity penalty.
Operators are also learning to plan for augmentation rather than replacement. Oversizing a block by 10–15% at commissioning and adding racks in years 8–12 is now standard practice for merchant and utility projects, preserving usable capacity while spreading capital expenditure. Documented performance from operating plant is available in our [project portfolio](/projects), which tracks capacity retention across multi-year deployments.
Residential and Commercial Systems in 2025
The residential segment has converged on 51.2 V nominal rack batteries in 100 Ah and 280 Ah formats, typically configured in 5–30 kWh stacks, alongside high-voltage architectures (100–400 V) that pair directly with hybrid inverters for higher round-trip efficiency. LFP's flat discharge curve and safety profile make it the near-universal choice for wall-mounted and floor-standing home units, and 2025 product cycles have pushed usable energy density to roughly 120–140 Wh/kg at the pack level with 6,000–8,000 cycle warranties and 10–15 year performance guarantees.
Commercially, the economics hinge on tariff structure. Behind-the-meter LFP systems in markets with wide time-of-use spreads or demand charges routinely achieve paybacks of four to seven years when paired with PV, and the addition of backup capability raises customer willingness to pay. Our [lithium battery product line](/products/lithium-battery) details the module formats, C-rates, and communications protocols (CAN, RS485, Modbus) that determine compatibility with third-party inverters.
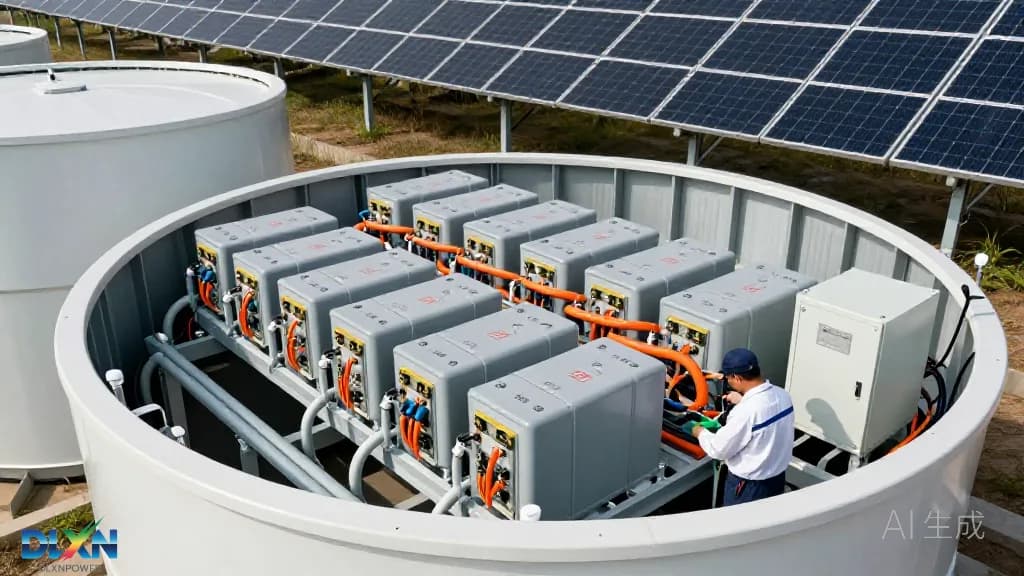
Solar-integrated architecture is also diversifying beyond rooftop. Carport-mounted PV with integrated LFP cabinets combines generation, shading, and EV charging at a single grid interconnection—an approach we deploy through the [EOS carport platform](/eos-carport). These projects illustrate a broader 2025 pattern: storage is increasingly specified at the point of generation, not as an afterthought in a separate enclosure.
Safety, Standards, and Bankability
LFP's thermal runaway onset temperature is materially higher than NMC's, and its runaway produces less energy and different off-gas composition—advantages that have reshaped codes. UL 9540A cell-to-grid-scale testing is now a de facto requirement for US projects, and NFPA 855 sets separation distances and fire-suppression expectations based on that data. IEC 62619 governs industrial cell safety, UL 1973 covers stationary battery modules, and UN 38.3 remains the transport gate. In 2025, an increasing number of jurisdictions also require fail-safe deflagration venting and gas detection.
Bankability has become the competitive battleground. Lenders and independent engineers now scrutinize warranty structures in detail: throughput caps, augmentation obligations, capacity retention thresholds, and the creditworthiness of the warranty provider. A 20-year, 70% capacity retention guarantee is only as valuable as the balance sheet behind it, which is why tier-one LFP suppliers publish audited cycle data and third-party test reports.
Regulatory momentum is adding traceability requirements. The EU Battery Regulation mandates carbon-footprint declarations, recycled-content minimums, and digital battery passports, while US domestic-content and foreign-entity-of-concern rules increasingly influence supply-chain qualification. For 2025 procurement, the practical advice is to specify LFP chemistry, liquid cooling, cell-level monitoring, UL 9540A or IEC equivalent test data, and a documented augmentation plan—then verify each claim against measured field data rather than datasheet cycle counts.